

terrier8797675
About terrier8797675
10 Reasons Why Having An Excellent Realestate Is Not Enough
There is a version of the housing market story that gets told over and over, and it goes like this: prices are high, rates are high, nothing is affordable, and the only people buying are the ones with cash. That version is not wrong, exactly. It is just incomplete.
The arithmetic here is brutal and worth understanding clearly. A buyer who financed a $400,000 home at three percent in 2021 pays roughly $1,686 per month on principal and interest. That same loan at a seven percent rate costs $2,661. The difference between those two payments explains why so many potential sellers are sitting tight. Volume collapsed. Prices mostly did not.
Here is what that creates for someone with solid credit and a real pre-approval in hand: a better chance of getting the house you want without losing a bidding war. The panic buyers are gone. The buyers who showed up with emotion instead of analysis have mostly sat back down. What remains is a more functional market, even if it is not a cheap one.
 Your credit score affects your rate more directly than most buyers realize. Moving your score up by 40 points before you apply can be worth more than months of rate watching. If your score has room to improve, give yourself three to six months to work on it before you begin in earnest.
 The appraisal is the lender’s check, not yours. If the home appraises below the contract price, the lender will only finance against the appraised value. Ask your agent what the local pattern looks like before you structure an offer without an appraisal contingency.
 Budget enough to cover origination fees, title, escrow, prepaid taxes, and insurance without being caught short at the table. First-time buyers routinely underestimate this number. Ask your lender for a Loan Estimate with a realistic purchase price so the numbers reflect what you are actually going to face.
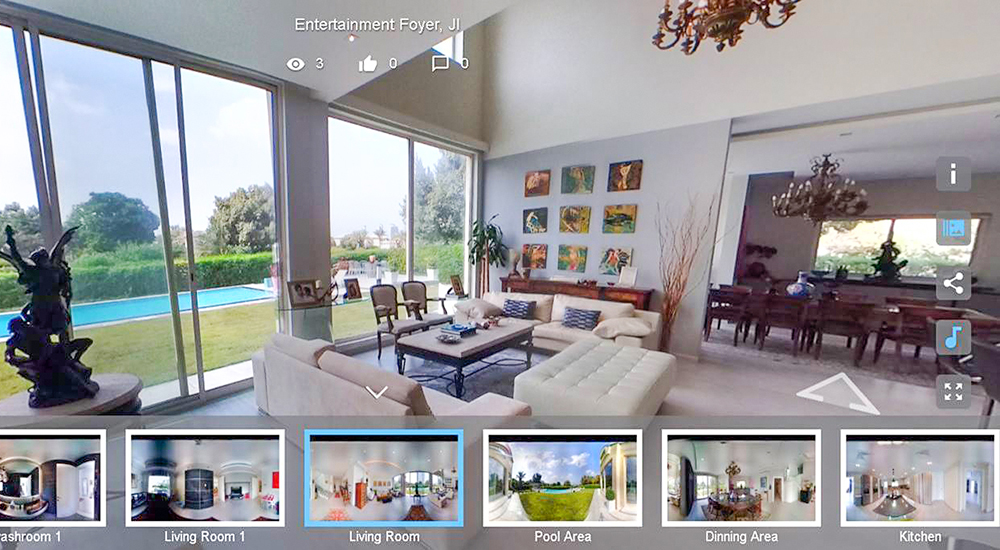 The timing question, whether to buy now or wait for rates to come down, is the one that trips up more buyers than any other single factor. The record on market timing for owner-occupied housing is not encouraging. The more useful question is not whether now is the right time in the abstract; it is whether the home works for your actual life for the next five to seven years.
Buyers who take the time to prepare before they start looking tend to find that opportunities exist even when conditions look difficult on paper. A quick look at up-to-date property listings will tell you more about your local market than most of what you read in national coverage.
No listing found.